
Mortgage Calculator
See your monthly payment, total interest and how your balance falls over time. Test overpayments, check a rate rise and get a rough idea of what you could borrow.
I'm Charles Calvert, a mortgage broker in Fareham. Put in the property value, deposit, rate and term to see what a mortgage could cost each month. The rate is just an example, so use one you've been quoted if you have it.
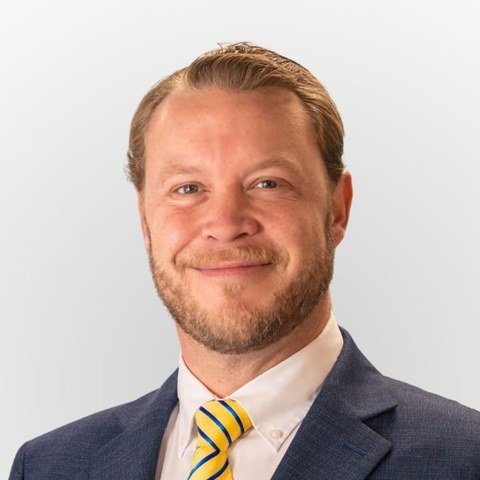
Thank you for using my calculator, I hope it was useful. If you have any questions or would like some advice on your own situation, just drop me a message or give me a call on 023 9355 2850. I’m always happy to help.
Charles CalvertMortgage broker, Easy Mortgages
Hampshire PO14 4SF
this calculator
Your mortgage
Enter the figures you're working with. Results update as you type.
Balance over time
Outstanding balance, with the interest and capital you pay each year.
Overpayments
See how paying a little extra cuts your interest and term.
Most lenders let you overpay up to 10% of the balance each year without an early repayment charge. Check your mortgage offer.
Rate rise check
What your payment could be if rates went up.
| Rate | Monthly | Change |
|---|
Borrowing guide
A rough idea based on an income multiple. A guide only, not a lending decision.
Lenders look at your full circumstances, including commitments and credit history. Speak to Easy for a proper affordability check.
Year-by-year schedule
Based on the figures above, without overpayments.
| Year | Paid | Interest | Capital | Balance at year end |
|---|
Like the numbers? Let's find you the right deal.
Charles compares lenders for you and handles the paperwork, from first chat to completion.
Repayment or interest-only: how your payments work
Repayment (capital and interest)
Each monthly payment covers that month's interest plus a slice of the loan itself. In the early years most of the payment goes on interest. As the balance falls, more of each payment goes on paying off the loan, until it's cleared at the end of the term. Borrowing £270,000 at 4.5% over 25 years works out at about £1,500.75 a month on a repayment basis.
Interest-only
You only pay the interest each month, so payments are lower, but the balance doesn't go down. The same £270,000 at 4.5% would be £1,012.50 a month, and you'd still owe the full £270,000 at the end of the term. Lenders will want to see a clear plan for paying it back, such as savings, investments or selling a property.
Overpayments, rate rises and your term
Paying a bit extra each month, or a lump sum, reduces the balance faster, so you pay less interest and can finish sooner. A longer term lowers the monthly payment but means more interest overall. The rate rise check shows how your payment could change if your rate went up, which is worth knowing before your deal ends.
What the calculator doesn't include
It assumes one rate for the whole term. Real deals usually start on a fixed or tracker rate and then move to the lender's standard variable rate. Lender fees, broker fees and insurance aren't included. My fees are set out up front, and product transfers have no fee. Your mortgage offer is always the figure to rely on.
Frequently asked questions
How is my monthly mortgage payment worked out?
For a repayment mortgage, the payment is set so the loan and all the interest are paid off by the end of the term. Interest is charged monthly at the annual rate divided by 12. For interest-only, the payment is the balance multiplied by the annual rate, divided by 12.
What's the difference between repayment and interest-only?
With repayment, every payment reduces what you owe and the mortgage is cleared at the end of the term. With interest-only, payments are lower but the balance stays the same, and you need a separate plan to repay the full loan at the end.
Does overpaying my mortgage save money?
Usually, yes. Overpaying reduces the balance, so less interest is charged from then on, and you can clear your mortgage sooner. Most lenders let you overpay up to 10% of the balance each year without an early repayment charge, but check your own mortgage offer first.
What is loan to value (LTV)?
Loan to value is your mortgage as a percentage of the property's value. A £270,000 mortgage on a £300,000 home is 90% LTV. A lower LTV usually gives you more lenders to choose from and lower rates.
How much could I borrow?
Many lenders start at around 4 to 4.5 times your income, but the real answer depends on your outgoings, credit history, deposit and the lender's own affordability checks. The borrowing guide above gives a rough idea, and my how much can I borrow guide explains it in more detail.
How these figures are worked out
- Repayment mortgages use the standard annuity formula with interest charged monthly at the annual rate ÷ 12. Interest-only payments are the balance × annual rate ÷ 12, with the full loan still owed at the end of the term.
- Figures assume the rate stays the same for the whole term. Real deals usually have an initial rate followed by the lender's standard variable rate. Fees, insurance and product charges are not included.
- Payments are shown to the nearest penny. Lenders may round slightly differently, so your mortgage offer is the figure to rely on.
This calculator is a guide only and is not advice. Figures are illustrations based on the information you enter and the rules shown above. They are not a mortgage offer, a lending decision or tax advice. Speak to Easy Mortgages for advice on your own circumstances.
Easy Mortgages Limited (FCA number 972959) is an appointed representative of Mortgage Intelligence Ltd which is authorised and regulated by the Financial Conduct Authority under number 305330 in respect of mortgage, insurance and consumer credit mediation activities only. You can check these details on the FCA Register at register.fca.org.uk. Registered address: 10 Merryfield, Fareham, Hampshire, PO14 4SF. Registered in England & Wales under number 13862954.