
Mortgage Capacity Reports for divorce and separation
A Mortgage Capacity Report shows how much you could realistically borrow after you separate, which lenders would lend it and what it would cost each month. I prepare every report personally for a fixed fee of £249, signed with a statement of truth and ready for Form E, your First Appointment, mediation or an FDR.
I’m Charles Calvert, a CeMAP-qualified mortgage broker in Fareham with nearly 20 years in mortgages. Whether you’re hoping to keep the family home or start again somewhere new, I’ll give you clear, honest figures you can plan around.
What is a Mortgage Capacity Report?
A Mortgage Capacity Report (MCR) is an independent assessment of how much you could borrow on a mortgage, based on your income, outgoings, credit history and the deposit or equity you’re likely to have after your settlement. You may also hear it called a mortgage raising capacity report, a mortgage capacity assessment or a mortgage capacity letter.
When a couple separates, the big question is often whether one of you can keep the family home, or what each of you can afford to buy. Your report answers that with real lender figures, not guesswork, so everyone can negotiate from the same facts.
Who needs one?
- Anyone divorcing, dissolving a civil partnership or separating who owns a home or wants to buy one
- Anyone hoping to keep the family home by buying out the other party
- Family solicitors and mediators who need borrowing evidence for Form E, the First Appointment or negotiations
- Both parties together, where a joint report has been agreed
- Anyone who needs a clear explanation of why a mortgage isn’t possible right now, and what could change that
Can I keep the house, or what could I buy?
These are the two questions I’m asked most after a separation. Your report answers whichever applies to you, or both.
Keeping the family home
To keep the home you’ll usually need to take the mortgage into your sole name and borrow enough to buy out your ex-partner’s share. I work out the buy-out figure for different equity splits, including any early repayment charges, and tell you whether a lender is likely to agree it on your income alone.
Buying somewhere new
If you’re moving on, I show the price you could afford with each equity split, together with example mortgage options, rates and monthly payments, so you can look at homes with confidence and back up your housing needs.
What’s in your report
A headline maximum and a realistic maximum, with the monthly payment and the term to your retirement age.
Lenders don’t agree. I show the figure from each lender I assess and explain what drives the difference.
Salary, overtime, bonus, self-employed income, benefits and maintenance, and how much of each lenders will use.
Buy-out figures for different equity splits, including early repayment charges, and whether each one is achievable.
The price you could afford with each equity split, plus example mortgage options with rates and monthly payments.
What your payments would be if rates rose by 1%, 2% or 3%, and what you would have left each month.
An itemised list of the evidence I checked, so nothing is taken on trust without saying so.
Every assumption stated openly, with how long the report is valid for.
Independence, duty to the court, conflicts of interest and a statement of truth, signed by me.
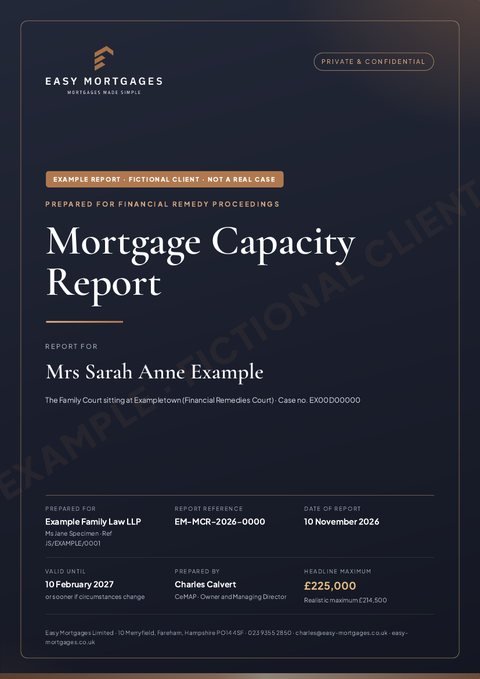
What a Mortgage Capacity Report looks like
This is the cover of an example report for a fictional client. Your report follows the same clear layout: a one-page summary with your headline figures first, then the detail behind them, so a judge, solicitor or mediator can find what they need quickly.
- Prepared for financial remedy proceedings, mediation or negotiation
- Signed by me, with a statement of truth
- Sent as a PDF to you, and to your solicitor or mediator if you’d like
How it works
Request online
Answer a few questions about your income, family, home and settlement. It takes about 15 minutes, and you can skip anything that doesn’t apply.
Send documents securely
I’ll send you a personal link to my secure client portal for your payslips, bank statements and ID.
I assess your case
I check the evidence, speak to you about anything unclear and run your figures with lenders across the market.
Your signed report
You receive a signed PDF report, and I can send it straight to your solicitor or mediator.
Price: a fixed fee of £249 per report.
Timescale: tell me your deadline, such as your First Appointment or FDR date, when you request the report. I’ll confirm when it will be ready once I have your documents.
For solicitors and mediators
I’m happy to take instructions direct from you, on behalf of one party or jointly. Please send your letter of instruction and any specific questions you need answering, and I’ll answer each one in the report.
Email charles@easy-mortgages.co.uk or call 023 9355 2850.
About me
I’m Charles Calvert, Owner and Managing Director of Easy Mortgages. I’ve worked in mortgages for nearly 20 years and I’m fully CeMAP qualified. I prepare every report personally. Meet Charles
Mortgage Capacity Reports in Hampshire and across the UK
I’m based in Fareham and help people going through a divorce or separation in Fareham, Portsmouth, Southampton, Gosport, Winchester and across Hampshire. Everything can be done by phone, video call, email and my secure client portal, so wherever you live in the UK, I can prepare your report without you needing to visit.
Ready to find out what you can borrow?
Fixed fee £249. Start your request now. Your answers are saved on your device as you go.
Mortgage Capacity Report FAQs
How much does a Mortgage Capacity Report cost?
A fixed fee of £249 per report. The fee is the same whatever the report concludes.
What is the difference between a Mortgage Capacity Report and a mortgage capacity letter?
A mortgage capacity letter, sometimes called a broker’s certificate, usually gives one headline figure. My report goes further. It shows the range across lenders, how your income has been treated, the monthly cost, buy-out figures if you want to keep the home, the documents I checked and every assumption I made, and it’s signed with a statement of truth. That gives your solicitor, mediator and the court far more to rely on.
When do I need a Mortgage Capacity Report?
Usually during financial remedy proceedings after a divorce or the end of a civil partnership. In England and Wales, the Financial Remedies Court expects both parties to file brief indicative material about their borrowing capacity at least 14 days before the First Appointment, and fuller evidence is often needed before the FDR. Many people also use a report in mediation, or to negotiate a settlement without going to court.
Is a Mortgage Capacity Report the same as a mortgage offer?
No. It’s my professional opinion of what you could borrow at the date of the report, based on lenders’ criteria and the evidence you provide. Any mortgage application would still need the lender’s full checks, credit search and valuation.
Will the court accept my report?
Courts expect each party to provide brief evidence of their borrowing capacity before the First Appointment, and my report is written for that purpose. It includes the documents relied on, the assumptions made, a range across lenders, declarations and a statement of truth. If the court gives permission for expert evidence, I can prepare it to the standard of Part 25 of the Family Procedure Rules and Practice Direction 25B.
Can I keep the house after divorce?
Possibly. To keep the family home you would normally need to take the mortgage into your sole name and borrow enough to buy out your ex-partner’s share, and a lender has to be satisfied you can afford it on your own. My report sets out the buy-out figure for different equity splits, including any early repayment charges, and says whether each one looks achievable.
How much can I borrow after divorce or separation?
It depends on your income, your outgoings and credit commitments, your credit history, your deposit or share of the equity, and each lender’s rules. Lenders differ in how they treat things like child maintenance, Child Benefit, Universal Credit, overtime and bonus, so the same person can get quite different figures. My report shows the figure from each lender I assess and explains what drives the difference.
Can I use my bank’s figure or an online calculator instead?
For early, indicative evidence it can sometimes be enough. But one bank’s figure or an online calculator only reflects that lender, and it doesn’t show the workings. When the figure matters to your settlement, a report that compares lenders and sets out its assumptions gives everyone more to rely on.
What documents will I need?
Usually photo ID, proof of address, your last 3 months’ payslips and your P60 (or 2 years’ SA302s and tax year overviews if you’re self-employed), 3 months’ bank statements, any benefit award letters, maintenance evidence, a full credit report and your current mortgage statement. The request form gives you a list tailored to your situation.
How long is the report valid for?
Normally 3 months from the date of the report, or until your circumstances or lenders’ criteria change. I can update it if your case runs longer.
Can you prepare a joint report, or one for both of us?
Yes. I can prepare a joint report for two applicants, or a report instructed jointly by both parties’ solicitors.
What if I can’t get a mortgage?
The report will say so clearly and explain why, for example because of credit history or income type. It will also set out what could help, such as a family member joining the mortgage, a longer term or a different settlement.
Do you only cover Hampshire?
No. I’m based in Fareham and help people in Portsmouth, Southampton, Gosport, Winchester and across Hampshire, but everything can be done by phone, video call, email and my secure client portal, so I can prepare your report wherever you live in the UK.
Do I have to use Easy Mortgages for my mortgage afterwards?
No. You’re under no obligation. If you would like me to arrange your mortgage when the time comes, I’d be glad to help.
Easy Mortgages Limited (FCA number 972959) is an appointed representative of Mortgage Intelligence Ltd which is authorised and regulated by the Financial Conduct Authority under number 305330 in respect of mortgage, insurance and consumer credit mediation activities only. A Mortgage Capacity Report is not legal or tax advice.